Resource limits are leading to today’s wars

Changing leaders won’t fix the underlying problems

Why are people around the world unhappy? Voters in the US have called for change. Rioters in Europe, India, and Bangladesh are also seeking change. I believe that the underlying issue is that the world economy has hit what has been called Limits to Growth. There are too many people for available resources, particularly extractable energy resources. While it may seem as if there are enough resources, they are not sufficiently affordable to the many poor people in the world. Resources in short supply include fresh water and many types of minerals, besides fossil fuels.

Multi-curve chart showing projected trends in resources, births, deaths, food and industrial output per capita, services per capita, population, and pollution from 1900 to 2100.
Figure 1. Base scenario from The Limits to Growth, printed using today’s graphics by Charles Hall and John Day in “Revisiting Limits to Growth After Peak Oil.”

Hitting Limits to Growth leads to a world without enough finished goods and services, such as food and affordable vehicles, to go around. It is easy to imagine many related outcomes:

  • More fighting among countries
  • More difficulty repaying debt with interest
  • More governments needing to cut back on promised benefits, such as pensions
  • Too few jobs that pay well
  • A desire for new governments that will fix these problems

This concerning situation has been forecast to hit about now, since the 1970s.

In this post, I will try to explain the situation. I will show evidence that limits are being hit about now. Hitting limits leads to not-enough-to-go around and conflict. In the future, these wars may be fought in ways that use less fossil fuel resources, but the underlying issues will not go away. The wars are likely to be fought until they are resolved, in one way or another.

[1] The economy is tightly interconnected in ways that are difficult for most observers to understand.

Our leaders would like us to believe that they are all-powerful, but unfortunately, their actions are limited by the resources that they have at their disposal. These resources include various types of energy resources, which unfortunately cannot easily be substituted for one another.

For example, today’s farming equipment typically uses diesel. A farmer using a shovel could perhaps provide the same services, but the farmer’s output per hour would be much lower using a shovel compared to using a diesel-powered tractor. Farmers and other workers are paid based on their output. It is no surprise that farmers prefer using diesel-powered tractors to produce food, rather than using their own manual labor plus shovels. Manual labor is, of course, another type of energy.

Figure 2 shows a chart illustrating the way I see the economy working. Fossil fuels, especially oil, are essential for the operation of today’s economy.

Slide explaining the economy as a self-organizing, fragile structure, illustrated by a colorful Leonardo Sticks toy labeled governments, consumers, businesses, energy products, wages and prices, and laws.
Figure 2. Illustration by author regarding how an economy tends to build up over time, and the impossibility of going backward.

Economies tend to grow as population rises, and as an increase in available resources makes possible a greater quantity of finished goods and services. Each new entrepreneur surveys the needs of his or her community and figures out what goods or services can be provided at an affordable cost. Governments gradually provide laws and public services to meet the needs of an expanding economy.

When certain types of goods are no longer needed, they tend to disappear from the market. For example, people no longer use horses for transportation. For this reason, buggy whips are no longer made at large scale. Also, the number of horses, relative to the human population, is much lower. It is not possible to resume using horses instead of cars because the situation has changed: Cities are much larger, there are few horses, and there are no services to remove manure from city streets. Because the system is always adapting to new situations, the system cannot simply go backwards.

Humans are the top predators in the world today. As long as there is sufficient food, water, and other needed supplies, the human population can grow, year after year. However, things tend to go wrong. If gathered wood is used for heat energy, nearby woods quickly get cut down, leading to a need to get wood from farther away, at a significant cost. If irrigation is used, the gradual accumulation of salts in the soil tends to reduce the harvest of barley and wheat. People living in close proximity tend to catch illnesses from each other, leading to epidemics. And the weather/climate tends to fluctuate.

Because of these and many other issues, economies are temporary. They tend to grow for a while. Then some combination of things goes wrong, causing them to collapse. Researchers have concluded that economies are self-organizing systems, powered by energy. They are subject to the laws of physics. They are not too different from plants and animals that grow for a while. Both may enjoy a stable existence for a while, before they decline and die.

Ultimately, economies that can no longer adapt to a changing situation are replaced by other economies that are better adapted to work with the available resources. We are now in the transition period between the integrated world economy of recent decades and the necessary replacement of that economy by one or more economies that are better adapted to declining fossil fuel availability.

[2] There seems to be a widespread belief that new leaders can somehow fix the world’s resource problems.

In my view, the belief that new leaders can fix the situation is false.

Slide asking what happens when oil supply falls too low, with answers that oil prices rise and the problem is quickly resolved.
Figure 3. Slide from Limits to Growth presentation by author.
Slide explaining why politicians and economists prefer the standard answer, while noting that simultaneous depletion of other resources and rising population produce a different result.
Figure 4. Slide from Limits to Growth presentation by author.
Slide explaining that rising prices outpace wages, prompting leaders to raise interest rates and potentially causing a recession.
Figure 5. Slide from Limits to Growth presentation by author.

What is needed are more inexpensive resources with which to make goods and services. There seem to be more resources available in the ground, but they are generally expensive-to-extract resources. The resources that were inexpensive to extract and transport were removed first and sold.

Adding money created through debt-based promises is no longer sufficient after a certain point. Instead, governments tend to collapse, or they are overthrown. They tend to be replaced by governments providing fewer services such as armies, schools, roads, and pensions.

[3] Some people seem to believe that the world’s energy problems are “only” a fossil fuel problem. They assume that these problems will disappear with the transition to renewables.

There are at least two problems with this belief.

  1. So-called renewables are, in fact, manufactured and maintained using fossil fuels. If we lose fossil fuels, we also lose renewables. We also lose nuclear power because building and maintaining nuclear power plants depends upon fossil fuels.
  2. So far, “renewables” have had a limited impact on total energy supply. They mostly “top-up” the fossil fuel supply.
Line chart showing fossil fuel share of total energy consumption in China, the world, the United States, and Europe from 1965 to 2025.
Figure 6. Fossil Fuels energy consumption as share of total energy consumption for selected areas, based on data of the 2026 Statistical Review of World Energy, published by the Energy Institute.

Based on data of the 2026 Statistical Review of World Energy, the world trend in energy consumption by type is as shown in Figure 7, below.

Stacked area chart showing world energy consumption by type from 1965 to 2025, dominated by fossil fuels with nuclear, hydroelectric, biofuels, wind, and solar contributions.
Figure 7. World energy consumption by type based on data of the 2026 Statistical Review of World Energy, published by the Energy Institute.

On Figure 7, nuclear provides the largest share of non-fossil fuel energy of the types shown, 5.2% in 2025. The various types of renewable energy shown, including hydroelectric, add up to 8.6% in 2025.

Wind and solar energy together amounted to 3.3% of the energy consumed in 2025. Their intermittency limits their usage. Solar energy is close to useless for providing heat for homes in winter, and not even wind cannot be depended upon in winter. This is why Europe, with its higher use of wind and solar energy, is dependent upon imported natural gas in winter.

Figure 7 shows that dips in fossil fuel consumption occurred in 2008-2009 and in 2020. When there is a major recession, or when people are ordered to stay at home, fossil fuel consumption (especially oil) tends to temporarily fall.

[4] A more recent recalibration of the 1972 Limits to Growth analysis suggests that limits to growth are hitting about now.

Figure 8 shows the summary chart from a paper titled, “Recalibration of limits to growth: An update of the World3 model,” by Arjuna Nebel and others, published in 2023.

Line chart titled “State of the World plot - BAU & Recalibration23,” comparing solid Recalibration23 and dotted BAU projections from 1900 to 2100 for industrial output, population, food production, pollution, and natural resources.
Figure 8. Summary chart of recalibrated Limits to Growth model by Arjuna Nebel and others, with Gail Tverberg’s labels showing which lines are “Industrial Output” and which are “Population.” Source.

Figure 8 indicates that we are currently experiencing the expected impacts of the Limits to Growth. The level of conflict is likely higher. It is not surprising the citizens are often unhappy with their current governments. Economies are on the edge of shifting toward contraction, rather than growth.

[5] Relative to world population, the quantity of steel produced, the quantity of cement produced, and the number of cars sold has been falling in recent years.

Line chart showing global crude steel production rising from 189 million tonnes in 1950 to 1,849 million tonnes in 2025.
Figure 9. World production of crude steel, by the World Steel Organization. Source.

Figure 9 shows that crude steel output since 2019 has been basically flat. World population has been rising during this time period. Thus, steel production per capita has been falling since 2019. This means that since 2019, there probably have been fewer cars manufactured and fewer home appliances made relative to the growing population.

Similarly, Our World in Data shows basically flat cement production since 2013.
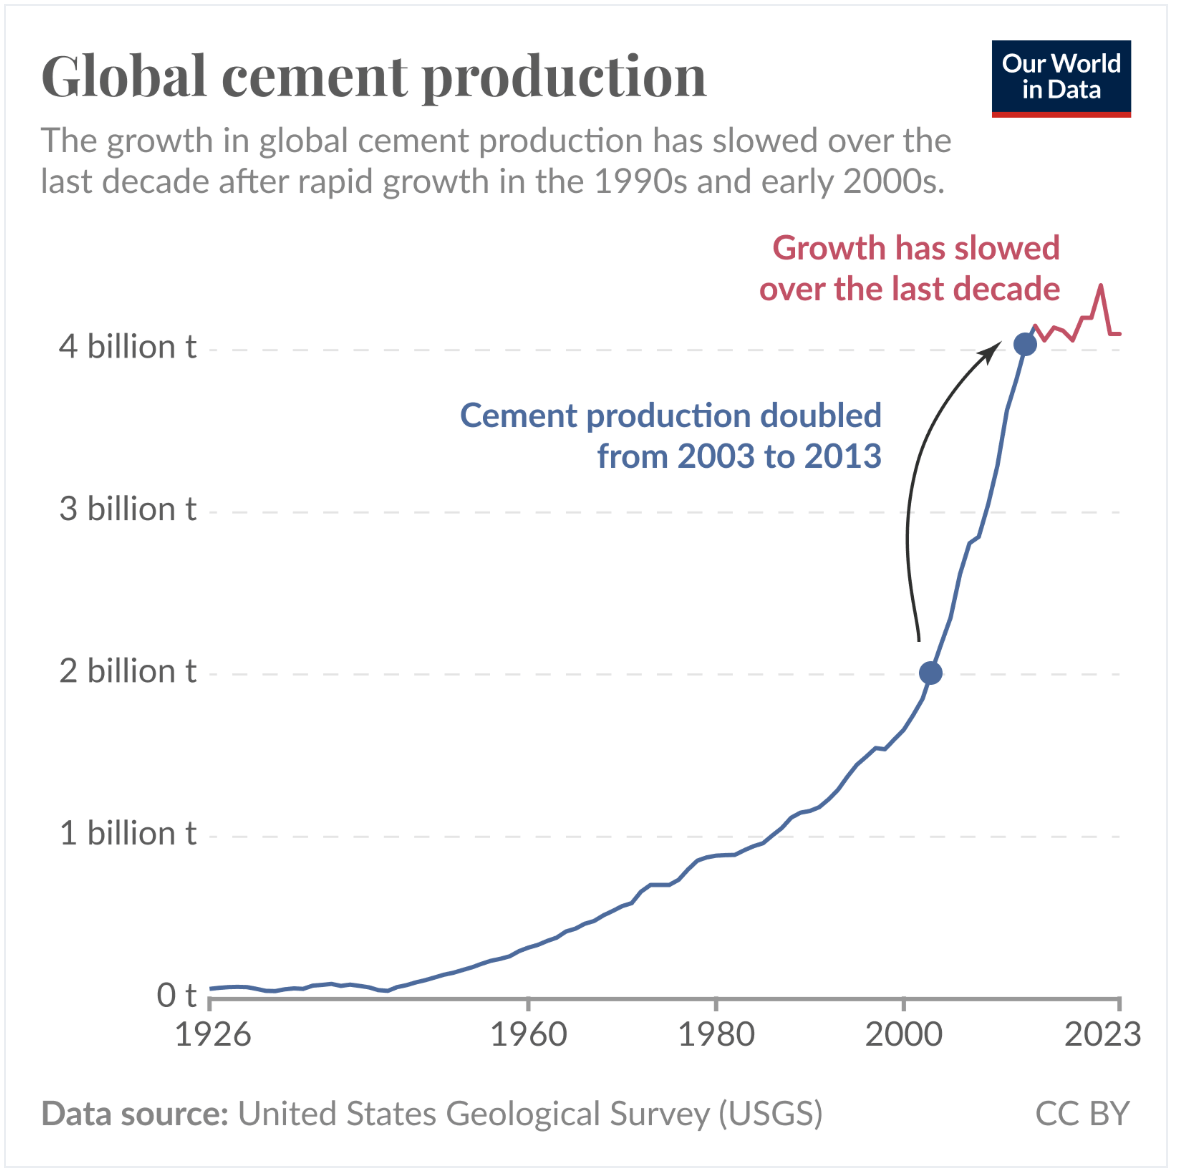
Line chart showing global cement production rising from 1926 to 2023, doubling between 2003 and 2013 before growth slowed in the last decade.
Figure 10. Global cement production chart, prepared by Our World In Data, based on USGS data.

We know that world population has been growing since 2013, so clearly the amount of concrete produced, per person, has been falling. Thus, finished output, such as new concrete roads and buildings per person, has been falling.

Similarly, the number of new cars sold stopped growing after 2017. New cars were becoming too expensive for potential buyers.

Stacked bar chart showing global new car sales by type from 2010 to 2025, with electric cars increasing and non-electric cars remaining dominant.
Figure 11. Number of new cars sold, by Our World In Data.

The number of cars sold is not as high in 2024 and 2025, as it was in 2017, despite rising population.

It is tempting to blame leaders for the problem: Better laws are needed. It seems like the rich with their high incomes are taking too much of what is available.

But the underlying problem is that there are not as many goods to go around as there used to be. Strangely enough, the way this works out in our tightly interconnected economy is that the wages of younger people are becoming lower, relative to the wages of their parents. They cannot afford to get married, have a home, and raise a family. What is missing is jobs that pay well, as well as the inexpensive energy of the right type that makes such jobs possible.

[6] One type of war being fought today is the type being fought by the military.

Today’s military wars seem to be fought by countries with flat to falling energy consumption per capita, against countries that, through 2025, saw rising energy consumption per capita. Figure 12 and 13 show comparisons that may be surprising:

Line chart comparing per capita energy consumption in Russia and Ukraine from 2000 to 2025, with Russia consistently higher than Ukraine.
Figure 12. Per capita energy consumption of Russia versus Ukraine, based on data of the 2026 Statistical Review of World Energy, published by the Energy Institute.
Line chart comparing per capita energy consumption in Iran and Israel from 2000 to 2025, showing Iran rising and Israel generally declining.
Figure 13. Per capita energy consumption of Iran versus Israel based on data of the 2026 Statistical Review of World Energy, published by the Energy Institute.

It is striking how in both Figures 12 and 13, nearby countries are observing opposite trends in energy consumption per capita. More energy consumption per capita tends to indicate a country that is doing better, economically.

Figure 12 shows that Russia’s energy consumption per capita has been growing, while Ukraine’s has been falling behind. It is almost as if one country’s increased consumption means decreased energy consumption for its neighbor. Figure 13 shows that Iran’s energy consumption per capita has been growing, while Israel’s has been falling behind. It is easy to imagine that competition for resources of all kinds underlies both conflicts.

China is not a direct competitor in the Iran conflict, but China and the US are competitors for resources of all kinds, (and, indirectly, jobs that pay well), in a kind of cold war. Here again, we observe the pattern of rising energy consumption per capita in China, and falling energy consumption per capita in the US.

Line chart titled “Per Capita Energy Consumption: China-US,” comparing China and US energy consumption from 2000 to 2025; China rises from about 30 to 115 gigajoules per capita while the US declines from about 335 to 270.
Figure 14. Per capita energy consumption of China versus US based on data of the 2026 Statistical Review of World Energy, published by the Energy Institute.

To the extent that China gets more of the resources, the US tends to get less. This is another conflict that can’t easily be resolved. There fundamentally aren’t enough minerals like antimony and nickel for every country to purchase what it would like. Moreover, copper is in too short supply for all nations to ramp up electricity usage at once.

Because of the problem of “not enough goods and services to go around,” it is difficult to see a solution to the conflicts in Iran and in Ukraine-Russia. However, the wars may take different forms. For example, it may be tempting for Iran to strike back against aggressors using AI to disrupt the internet, electricity, or fresh water supplies. Europe has already seen bomb threats against airliners. There may be assassination attempts against leaders. These are lower-energy types of wars. It is possible that the two wars will merge to become a hidden World War III. In fact, China may also join in a way that allows the conflict to become a true world war.

[7] A second type of war relates to the share of a country’s income that should go to benefits provided by the government and the share left for the individual citizen to spend.

If countries are growing rapidly, thanks to a very rapidly growing supply of inexpensive energy, it can temporarily look like governments can afford very generous programs of many kinds for their people. For example, it will look like governments can support pensions, healthcare programs, unemployment programs, educational programs, and road repairs, without a very high tax level. This was the situation in the years following WWII in many countries.

Unfortunately, as Limits to Growth modeling shows, things change. Gradually, fossil fuel energy supplies deplete and population grows. Available oil supply becomes more expensive and grows less rapidly. This combination means that major program cutbacks are needed to make whatever services are provided to the citizens also affordable by them. Before fossil fuels became available, pensions for common citizens were unknown.

Newly elected leaders would like to change their economies in a way that will maintain (or even increase) promised programs but, because of Limits to Growth, we are reaching a point where this becomes impossible. Debt levels are already too high to support much additional borrowing. If a new leader tried to significantly reduce current programs, citizens would likely revolt. Unfortunately, even a revolution won’t create the physical goods and services needed to allow promised programs to continue. Raising taxes to provide all the benefits citizens expect would leave the people with virtually no income for daily living after taxes.

What history shows is likely to happen is that at some point, either (a) the financial system of a country with excessive promises will collapse, or (b) the country will lose at war. At some point, a new economy will arise, with many fewer promises. For example, if the EU were to collapse, the individual countries of the EU might take on additional roles. If an individual country such as France were to collapse, the regional governments might take on additional responsibilities. But they are unlikely to provide nearly as broad a package of benefits as before the collapse.

To keep resource needs down, the new governments are likely to have many fewer employees. In many cases, the new leaders will not be elected. The new leaders might be winners at war, or they might be self-appointed.

[8] A third type of war relates to the level of complexity an economy should have. This tends to lead to internal warfare.

Complexity can be good. For example, it can give consumers useful devices at low prices. It can sometimes lead to reduced energy consumption in a particular device.

But complexity can have unintended bad side effects. One issue is wage disparity. With greater complexity, businesses tend to become larger and more hierarchical. The top people tend to be paid much more than those at the bottom. Competition is often against low-wage countries. Such competition tends to bring down the wages of unskilled workers. The use of AI can sometimes eliminate jobs completely.

Another issue of added complexity is that it tends to lead to wealth disparity. Those with higher wages can afford to buy homes and shares of stock. If prices of homes and shares of stock increase over time, those who are already rich tend to become even richer. Eventually, these high home prices become unaffordable by the many less-wealthy people.

At some point, poor people become frustrated with the situation. They want to fix it. They riot. They start burning cars and buildings. Instead of fighting against other countries, the problem becomes internal conflict.

The economies of countries whose governments collapse generally fall back to a lower level of complexity than they had previously. Taxes then become lower. This can be good. But resource problems don’t go away by themselves. Some types of new solutions, probably with added complexity, are needed to work around resource problems, if this is possible.

[9] Conclusion

No one tells us that, at some point, the economy is likely to take a turn for the worse, but that seems to be the situation we are reaching. There now seem to be too few physical resources for the current number of people in the world to live at the standards of living that they are accustomed to. Renewables haven’t solved the problem, and more debt by governments cannot solve this problem.

Many people hope that electing new leaders will fix the situation. Because the underlying problem is really a resource problem, this cannot really help. Eventually, many governments are likely to collapse, unless solutions to our resource problems are found.

Quite likely, international fighting will continue, and it may even spread to become World War III. However, because of resource limits, this war will be fought in a less resource intensive way than it has been to date.

It does not look like complexity can be sustained in the way that it has been adopted to date. If this is the case, in its next stage, the world economy is likely to fall back to a lower level of complexity than exists today. The big plus of lower complexity is that taxes are likely to be lower. However, the change will require adaptation.

Posted in Financial Implications, News Related Post, Planning for the Future | Tagged , , | 79 Comments

Can the diesel and jet fuel shortage be solved?

The nature of the shortage of diesel and jet fuel is more complex than most people realize. Based on my analysis, a shortfall has existed since at least 2020. The shortage is not simply the result of the closure of the Strait of Hormuz.

In this post, I will provide background information regarding the nature of the shortfall and the international conflict it is leading to. I will also share my thoughts on how, over the long term, the situation might be mitigated. I doubt whether a solution will be available in the short term, but I can at least give readers an idea of one direction in which a possible workaround might be available.

My idea is that the economy needs to transform itself in a way that uses diesel and jet fuel (grouped together on some reports as “middle distillates”) more sparingly. At the same time, research on extracting heavy oil and bitumen at lower cost is needed. If this is done, it may be possible to use additional heavy oil to increase the supply of diesel and jet fuel.

One thing that will probably need to change is the price of diesel relative to gasoline. The price difference will likely need to be even greater than it has been in the recent past because heavy oil is inherently more difficult to extract, refine, process, and transport.

[1] The interconnected nature of the economy means that inexpensive energy products are extremely important to the economy.

Energy supply and the economy are a great deal more interconnected than most people realize. For example, if the price of diesel rises, the price of food also tends to rise because diesel is used in food production and transportation. Similarly, if the price of gasoline rises, the additional cost also tends to squeeze budgets. Politicians see these price increases and say to themselves, “These increases will make voters unhappy. Let’s raise interest rates and see if we can get oil prices back down.”

Higher interest rates don’t affect everyone immediately, but they particularly impact people purchasing a vehicle or a home, and businesses seeking a loan.

A comparison of budget expenditures under low and high oil prices, illustrated with two pie charts showing the distribution of costs for food and gasoline, debt payments, and everything else.
Figure 1. Slide by author, illustrating the impact that rising debt payments taking place at the same time as rising energy costs pose to household budgets.

Clearly, raising interest rates at the same time as energy prices are rising is “playing with fire.” If the economy is really overstimulated and growing too quickly, this type of approach makes sense. But if the underlying problem is that diesel and jet fuel prices are high because of inadequate world production, what is really needed is higher oil prices, especially for the heavier crude oils that provide a disproportionate share of diesel and jet fuel.

Consumers and oil producers have two different needs for prices:

  • Consumers want diesel and jet fuel prices low because high prices wreck their budgets. Diesel is used in growing food and transporting it to market. Jet fuel is used in transporting some kinds of foods. In fact, industries of all kinds (including mining, road building, and construction) use diesel and jet fuel. Higher prices of these fuels tend to make practically any kind of goods or services more expensive.
  • Oil producers want diesel and jet fuel prices high, to incentivize investment in new wells. Without additional investment, the quantity of heavy oil extracted and made into these fuels will tend to decrease because of depletion issues.

While prices for diesel and jet fuel are higher this fall, quite a bit of the extra charges relate to extra transport and insurance costs. The high prices need to stay, and perhaps even increase, even if the immediate issues disappear, in order to incentivize greater long-term production. It is these rising prices that are likely to continue to squeeze budgets and push economies toward recession.

[2] What we call “oil” can vary quite widely from well to well. The trend over time has been toward lighter crude oils.

Most people assume that all oil is equivalent, but this is not the case. Petroleum is a mixture of hydrocarbon molecules. The lightest ones are gases are room temperature, the medium weight ones are liquids, and the heaviest ones tend to be quite viscous. Some are even solids. Some oils, especially heavy oils, have sulfur or metal inclusions. Crude oil that contains sulfur is called “sour oil.”

Heavier oils are ones that disproportionately produce diesel and jet fuel. Lighter oils tend to produce more gasoline, along with products like solvents, and the feedstocks for plastics.

In my view, a major reason why there tends to be a shortfall in diesel and jet fuel production (even apart from the current Middle East blockages) is that the type of oil needed tends to be more expensive to extract, refine, and transport than light oil. Furthermore, oil with sulfur tends to be quite corrosive, and removing the sulfur adds another layer of costs. The primary issue I see is that it is hard to pass on the higher production costs of heavy and sour oils to customers.

In theory, to cover all the costs involved related to heavy and sour oils, diesel and jet fuel prices should be quite a bit higher than gasoline prices for the same volume (liter or gallon). But if this were the case, the price of food would also increase, since diesel is extensively used in food production and transportation.

Figure 2 shows end products from the production process. We know, however, that lighter end products tend to come from lighter crude oils, so we can deduce that the crude oil mixture has been getting lighter over time. The amounts in Figure 2 include natural gas liquids, which are very light and growing in quantity.

Chart depicting world per capita oil consumption by end product from 1980 to 2025, showing various categories including Very Light, Gasoline, Diesel and Jet Fuel, and Very Heavy, measured in gallons per person per year.
Figure 2. World per capita oil consumption (including natural gas liquids) by end product based on data from exhibit “Oil: Regional Consumption by Part” from the 2026 Statistical Review of World Energy, published by the Energy Institute. Amounts are measured by volume, not energy production.

The earliest oil that was extracted tended to be “medium oil,” which tended to have a mixture of heavier and lighter molecules. As the medium oil depleted, new production tended to be lighter. In particular, US tight oil from shale is quite light. The increasing production of US tight oil from shale is adding to the Very Light layer, as well as the Gasoline layer.

[3] The world had a diesel and jet fuel shortage long before 2026.

Because of the need for diesel and jet fuel in industry and transportation, a person would expect per-capita diesel and jet fuel consumption to grow as industry and international trade grows.

Line graph showing world per capita consumption of diesel and jet fuel from 1980 to 2025, measured in gallons per year per capita, with a slight decline in recent years.
Figure 3. World per capita consumption of diesel plus jet fuel based on data from the sheet, “Oil: Regional Consumption by Part” in the 2026 Statistical Review of World Energy, published by the Energy Institute.

Figure 3 shows that per capita consumption of diesel and jet fuel stopped growing about 2005. The year 2005 seems to be the time that the world’s output of “conventional” (easy to extract) oil reached a peak. Figure 3 also shows that per capita consumption then plateaued until about 2019. It fell 16% in 2020, and it has not been able to fully recover since. The historical data on this chart is only through 2025, but the big Middle East cutbacks in 2026 will clearly send diesel and jet fuel consumption down from the 2025 level in 2026, as indicated by the red arrow.

At least in part, what is happening is that recent oil prices have not been high enough for countries producing somewhat heavy, sour oil. This is especially the case for oil exporting countries that depend on oil revenue to support their economies. They need more revenue than just enough to cover the cost of extraction, plus a reasonable return for shareholders. They also need money to fund the development of make-work projects to employ their citizens and to fund subsidized imported food for their population.

In the peak oil community, there seems to be the view that Middle East oil is always cheap to extract and refine. At one time, this may have been true, but most analyses overlook the tax needs of oil exporting countries. Tax needs are high in countries with exploding populations who need subsidized imported food. Huge make-work projects to provide employment possibilities, such as Saudi Arabia’s construction of the city Neom, add to the need for higher tax revenue. Middle Eastern oil costs may also be rising because of depletion issues, such as wells yielding relatively more water in the oil/water mixture extracted.

[4] For oil exporters, one symptom of chronically inadequate prices for heavy/sour oil (including the need for high tax revenue) is the willingness to engage in war.

If a person looks through my suggested list of heavy/sour oil producers shown on Figure 4, all the countries seem at least somewhat war-like. Even Canada tends to be war-like. Canadian leaders would be much happier if the price of crude oil exported to the US were considerably higher, and it would be less inclined to seek export partners in Asia and Europe.

Line graph showing oil production trends in million barrels per day for heavy/sour oil countries from January 2016 to January 2026, highlighting data for the Middle East, Russia, Mexico, Canada, and Venezuela.
Figure 4. Recent crude oil production by countries whose oil tends to be heavier and/or sour, based on monthly oil production data of the EIA. Middle Eastern oil tends to be medium sour. I may have omitted some heavy/sour countries.

If the oil production of the heavy/sour countries and country groups found on Figure 4 is added together, the result is as shown in Figure 5. The total production of these countries exceeds the production of the rest of the world.

Notice that the countries of the Middle East tend to be quite price sensitive. Their production dropped steeply in 2020 when oil prices fell. Likewise, their production rose in 2022 when oil prices were temporarily higher, related to the start of the Ukraine-Russia conflict.

Line graph showing global oil production from January 2016 to January 2026, comparing Heavy/Sour Oil countries (orange line) and Other Countries (blue line), measured in million barrels per day.
Figure 5. Monthly world crude oil production of the total of the countries shown in Figure 4, compared to the monthly crude oil production of the rest of the world based on data of the EIA.

[5] Authorities claim that there would be plenty of heavy oil to refine if prices were to rise high enough for long enough.

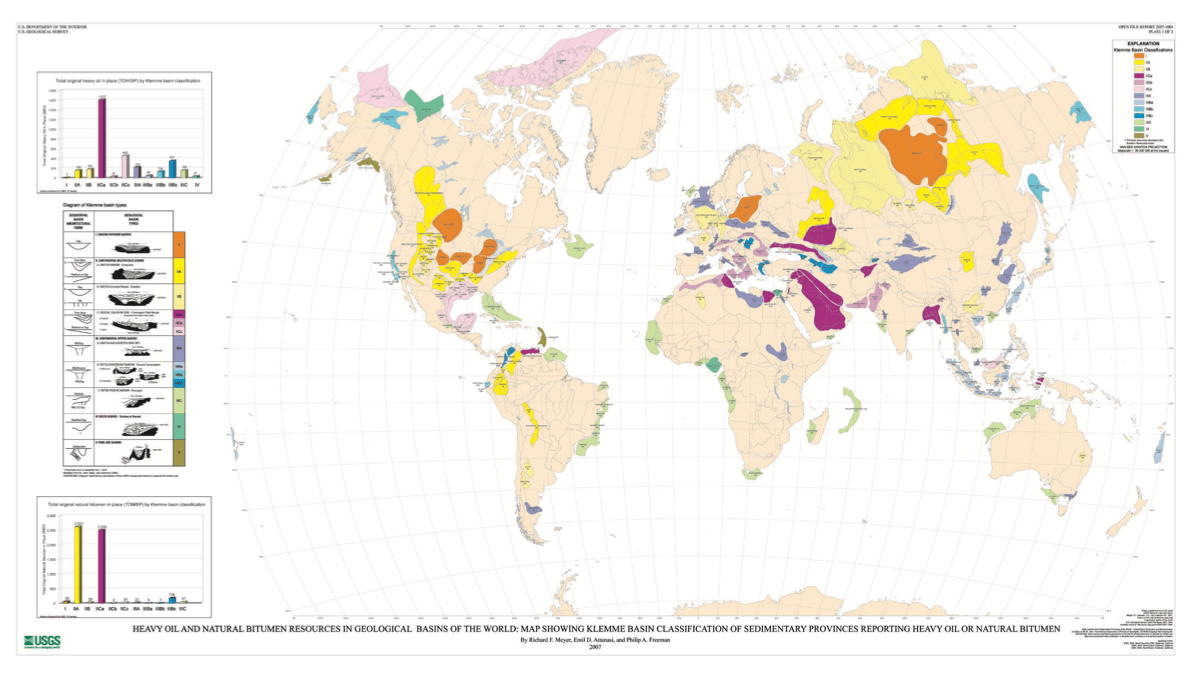
The United States Geological Services provides maps of available heavy oil and bitumen deposits. Figure 6 indicates that heavy oil is widely available in North America, Europe, Russia, and the Middle East.

World map showing sedimentary basins with heavy oil and natural bitumen resources, featuring color-coded regions based on resource classification. Includes graphs illustrating total original oil in place and diagrams of various basin types.
Figure 6. Map of Heavy Oil and Bitumen Resources by USGS. Source: Open File-Report 2007-1084

In 2015, the International Energy Agency published a report indicating that in its view, there were huge deposits of extra heavy oil and bitumen (EHOB) that could be accessed if the price of oil rose high enough for long enough (Figure 7). The same exhibit shows somewhat smaller availability of tight oil from shale. In fact, the US has been able to access a substantial amount of tight oil from shale in recent years.

Graph depicting non-OPEC supply cost curves for oil from 2015 to 2040 in the New Policies Scenario, showing oil prices per barrel against recoverable resources in billion barrels. It includes lines for conventional crude, tight oil, and extra-heavy oil and bitumen, with a vertical line indicating production needed by 2040.
Figure 7. IEA Figure 1.4 from its World Energy Outlook 2015, showing how much oil can be produced at various price levels.

In my opinion, in order to access the EHOB, the prices of diesel and jet fuel need to rise to a high level over the long term; the prices of gasoline and even lighter products don’t necessarily need to rise. If the prices of diesel and jet fuel rise high enough, for long enough, the price signal should work its way back to oil and gas companies, suggesting that they need to make investments in the direction of adding more extraction from EHOB. If this succeeds, it could perhaps relieve the problem of inadequate supply of diesel and jet fuel.

The prices of diesel and jet fuel are high now, but this is at least partly due to higher insurance costs and partly due to the extra costs related to shipping oil longer distances to avoid blocked straits. These extra costs don’t get back to oil companies in a way that encourages countries to extract more heavy oil. What is needed are permanently higher prices for diesel and jet fuel, relative to the price of gasoline, even if the problems with respect to the straits of Hormuz and of Bab al-Mandab, disappear.

[6] Today’s conflicts in the Middle East and Russia/Ukraine seem to relate to inadequate supplies of diesel and jet fuel for buyers of these fuels, and inadequate prices for sellers of the heavy/sour oils yielding these products.

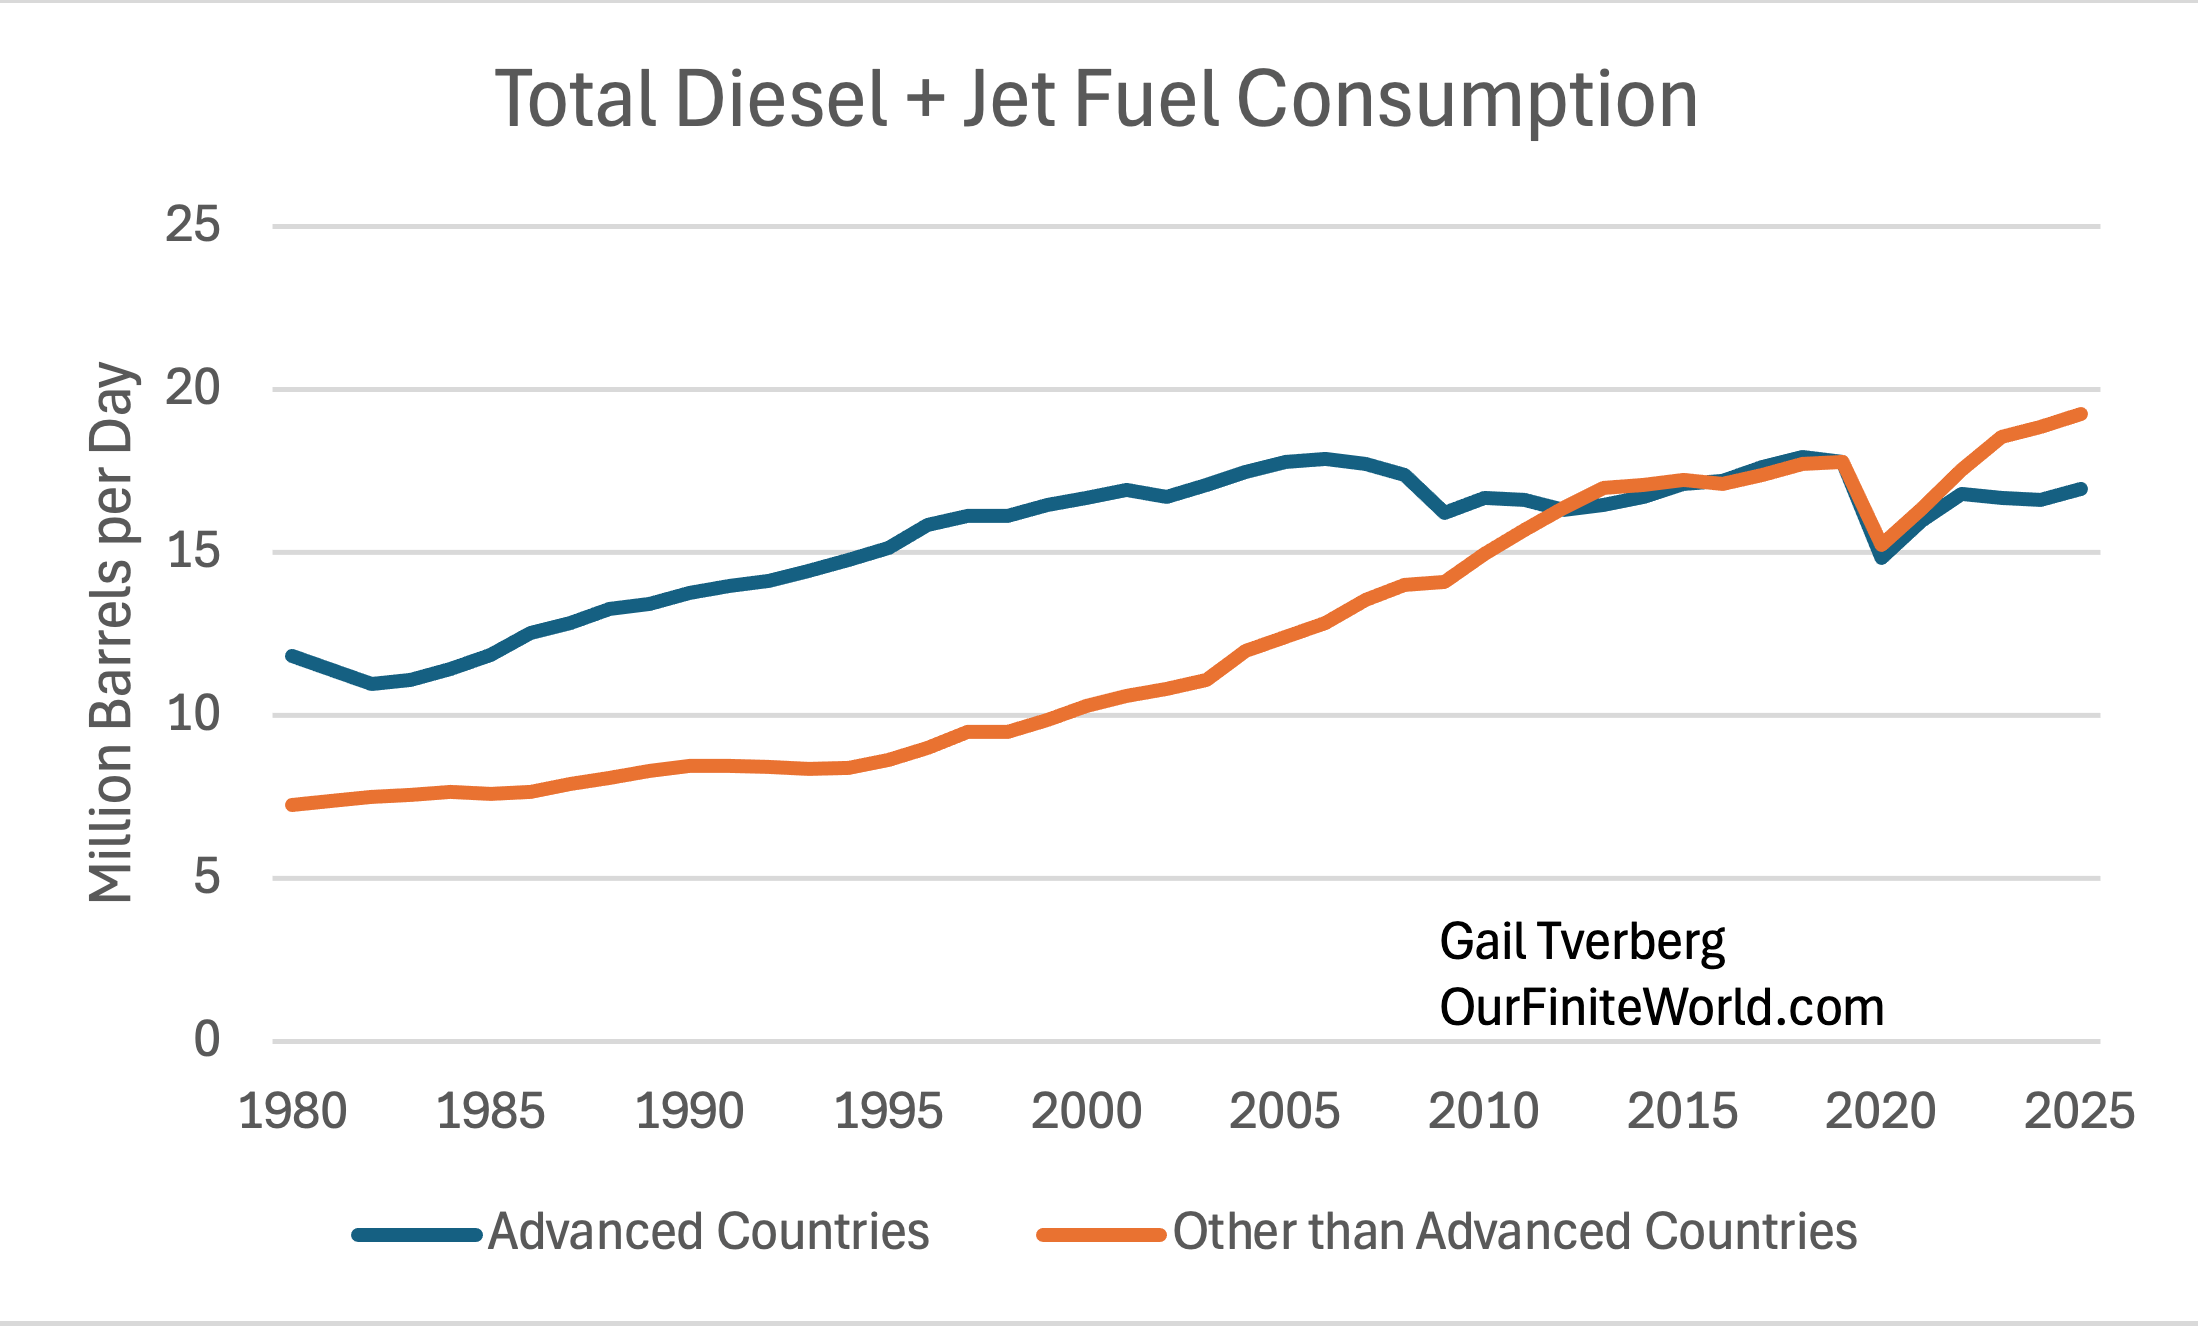
Figure 3, above, shows that the total supply of diesel plus jet fuel has been low, especially since 2020. One issue that has arisen recently is “Who gets the supply of diesel plus jet fuel that is available?” Figure 8 shows that increasingly, it has been the poorer countries of the world who obtain the diesel and jet fuel that is available. Note that total consumption of the Other than Advanced Countries has exceeded that of the Advanced Countries since 2020.

Line graph showing total diesel and jet fuel consumption from 1980 to 2025, comparing advanced countries (blue line) and other countries (orange line), measured in million barrels per day.
Figure 8. Diesel + Jet Fuel consumption for the Advanced Countries (OECD members), compared to that for the Other than Advanced Countries, based on data from the sheet, “Oil: Regional Consumption by Part” in the 2026 Statistical Review of World Energy, published by the Energy Institute. China, Russia, and Iran are in the “Other than Advanced Countries” group. The US, Israel, and NATO countries are in the Advanced Countries group.

Figure 9 shows that for the Advanced Economies, per capita consumption of diesel plus jet fuel has been declining since about 2005–the time of peak conventional crude oil. The same figure shows that per capita consumption of diesel plus jet fuel has plateaued since 2013 for Other than Advanced Countries. I think of 2013 as the year that China first started encountering major limits on coal extraction (somewhat like the year 1970 in the US for oil extraction). In recent years, China has been able to raise coal extraction somewhat, but at a higher cost.

Line graph showing per capita consumption of diesel and jet fuel from 1980 to 2025, with two lines representing advanced countries and other than advanced countries. Advanced countries' consumption is significantly higher than that of other countries.
Figure 9. Per capita consumption of diesel + jet fuel consumption for Advanced Countries (OECD members), compared to that for Other than Advanced Countries, based on data from the sheet, “Oil: Regional Consumption by Part” in the 2026 Statistical Review of World Energy, published by the Energy Institute.

I would expect that countries in both groups would be dismayed by the situation shown in Figure 9. The per capita consumption of diesel plus jet fuel for the Advanced Countries has been falling for a long time. Partly this is the result of the economies changing to service economies. As service economies, the need for diesel by industry has been lessened. Wages tend to be less for many of these service jobs, making workers unhappy.

In Figure 9, people in the Other than Advanced Countries would tend to be dismayed by the continued wide gap between the standard of living of their own economy, and the standards of living in the Advanced Countries. Many of these countries export extracted resources that are ultimately sold as goods to people living in Advanced Countries. If the selling prices of these commodities were higher, workers in these countries could perhaps afford to have cars and air conditioning, like workers in the Advanced Countries. They would also be dismayed by the poor progress in raising their own per-capita consumption of diesel and jet fuel since 2013.

[7] Is there any possibility of greatly ramping up heavy oil production? Could it power a society like the one we have today?

We know that heavy oil production began long ago. For example, the first recorded production of heavy oil began in the Kern River Basin in California in the 1860s, and commercial production began there in 1899. The first production in the Canadian Oil Sands began in 1921, and commercial production there began in 1967.

The extent to which the oil that is heavy and often sour can be ramped up in the future remains to be seen. Extraction techniques have gradually been improving, and I would expect that they can continue to improve. But the cost of extraction and processing will likely remain somewhat high because of all the energy-intensive steps that are needed to provide diesel and jet fuel.

I expect that society itself will need to change in order to make use of this higher-cost oil. These are a few ideas I have:

(a) Oil exporting countries will need to change in ways that reduce their need for tax revenue. This is an issue especially in the Middle East, which has a huge population, in a hot, dry climate. The population will likely need to fall (for example, many migrants and guest workers may need to move back to their country of origin), and make-work projects will need to be discontinued.

(b) Another issue is that total diesel and jet fuel usage will likely need to be reduced because it is likely to take several years before production of heavy oil can be ramped up. Society will need to be reorganized in a way that uses less diesel and jet fuel. One idea would be to shorten supply chains whenever possible. Figure 10 illustrates one idea how this might be done.

World map with North America and East Asia highlighted in yellow, showcasing geographical locations.
Figure 10. Map of the world showing how the author expects the United States and China might split most world trade. Most trade would take place within the two areas shown. Within these groupings, the centers of trade might be the yellow areas shown.

(c) I expect that if such a change can be made, economies will need to gradually change in ways that are hard for us to understand now. The focus may need to be on essentials, including food and clothing. Governments may need to be smaller and provide fewer services. Communities may need to be smaller and more walkable. The total population may need to be lower.

[8] Conclusion

It seems to me that the self-organizing nature of economies will gradually push them in the directions they need to go if the world is to start incorporating a significant quantity of expensive products made from heavy oil into its energy mix.

We cannot yet imagine what all the changes will look like. In some ways they may resemble a recession, but there will likely still be an interest in greater complexity and in working to improve people’s lives.

Posted in Financial Implications | Tagged , , , | 2,950 Comments

Affordability, Not Scarcity, Is the Real Energy Crisis

History back to 1820 gives hints regarding what may follow

With the recent closure of the Strait of Hormuz, many expect oil prices to spike and stay high. Instead, they have barely budged. The latest spike in prices is a mini spike. If these oil prices were adjusted for inflation, the spikes in the past would appear even higher.

Figure 1. Weekly average oil prices for West Texas Intermediate oil in a chart provided by EIA, with Iran conflict price spike circled.

This is not a new problem. Looking at energy data going back to 1820, low demand (affordability) has repeatedly produced financial crashes, wars, and collapses. We appear to be entering another such period.

In this post, I examine differences in how the economy behaves, comparing two different types of periods: those with low energy affordability (“low demand”) and those with high energy affordably (“high demand”). I also offer my view on what this analysis suggests may be ahead for the world economy.

[1] How high demand differs from low demand

High demand looks like a situation in which, each year, an increasing number of people can afford cars and the fuel that they require. With high demand, the number of new cars sold each year tends to rise. Young people are eager to buy homes because they find homes affordable. They find their incomes relatively higher than their parents’ were at their age. Countries around the world find it easy to industrialize. This allows their citizens to have better lifestyles. As we will see later in this post, the periods of the 1950s, 1960s, and 1970s were periods of high growth in demand for oil products.

What we have now is the opposite: too many young people who cannot find jobs that pay well, even with advanced degrees. They cannot afford to go on a vacation or buy a new car. Record numbers live with their parents after they finish their schooling. They spend their spare time playing video games, rather than socializing with their friends.

The number of cars sold worldwide hit a peak in 2017, indicating indirectly that people are getting poorer. If people are not buying as many cars, demand for oil tends to fall, especially if more of the cars that are sold are electric.

Building new homes also takes oil. According to the US Census Bureau, the number of US new homes sold in the US hit a record of 1,283,000 in 2005. In 2025, the number of US new homes sold amounted to only 678,000, or about 53% of the peak amount. The huge drop in new home construction is a sign that people, quite often young people, are not as well off financially as they were years ago. They cannot afford to buy a new (or even a used) home anymore.

One study based on income tax data revealed that between 1948 and 1970, US incomes tended to rise faster than inflation. Between 1968 and 1983, the incomes of both the top 10% and the lower 90% rose as fast as inflation. However, between 1983 and 2012, the top 10% received far greater increases than the bottom 90% (Figure 2).

Figure 2. Chart comparing income gains by the top 10% to income gains by the bottom 90% by economist Emmanuel Saez. Based on an analysis of IRS data, published in Forbes.

If workers in the bottom 90% of the distribution are not doing well, it is difficult to keep prices of commodities as high as those producing the commodities would prefer. Purchases of commodities, including food, and fuel for vehicles, do not rise proportionately with huge incomes. Elon Musk and other very high-income individuals do not spend all day eating or driving their vehicles. The bottom 90% must prosper for demand (affordability) of oil and other commodities to stay high.

[2] What experience with high and low growth in energy supplies since 1820 teaches us.

Several years ago, I prepared an analysis of how the world economy behaved over the long term, over the period from 1820 to 2017. I have recently updated this study. I found that the economy behaved quite well in times of high energy consumption growth. In times of low energy consumption growth, there seemed to be many adverse events, such as financial crashes, wars, and government collapses.

I am afraid that with today’s oil and debt problems, we are headed into a pattern of low energy consumption growth, or even energy consumption contraction. If this is the case, we should expect outcomes at least as undesirable those experienced during past periods of low energy consumption growth in the past.

(a) Methodology

I first prepared a new data set by combining two data sets, the earlier of which was available only every 10 years, with more recent data available more frequently. The energy quantities reported were rising rapidly. To analyze how fast they were rising, I first computed the average annual increase percentage for each 10-year period, as shown on Figure 3.

Figure 3. Average annual growth rate in world total energy consumption, for 10-year periods, except the latest period which is only 7 years. Energy growth estimates are based on data from Energy Transitions: History, Requirements and Prospects (Appendix) by Vaclav Smil for older years, and data from BP’s Statistical Review of World Energy for 1965 and subsequent. From this presentation.

For example, the period from 1961 to 1970 (shown as the 1970 bar) had a very high annual rate of growth rate for energy consumption. This was the period when many of the interstate highways in the US were opened and many pipelines were added.

On Figure 4, I divided the bars shown on Figure 3 into two parts.

Figure 4. The blue bars on this chart represent the average annual increase in population, over the period indicated. The red bars represent the amount of the growth in energy consumption left over for growth in standards of living. Energy data is the same as in Figure 3. Population estimates for 1940 and prior are by Angus Maddison; estimates for more recent years are based on UN data.

On Figure 5, the blue portions of the bars represent the average annual increase in population over the 10-year period. The red portion of the bar is computed by subtraction from the total. It is the amount that seems to be left over for a rising standard of living. Having a tall red portion of the bar would be very good; having little or no red bar left would represent a problem. Note that in two periods (the one ended 1860 and the one ended 2000), the amount left over for an increase in living standards was negative.

(b) Good things happened in years with very high growth in “Living Standards”

Figure 5 shows the information on Figure 4 as an area chart.

Figure 5. Chart from a 2018 presentation using the same energy data as Figures 4 and 5, with some of the related events marked.

While I don’t show oil prices on Figure 5, those who are familiar with oil prices will remember that high oil prices were a feature of the 1973 to 1981 period. Also, as China began its growth period, another spike in oil prices took place. High growth in energy supplies and high oil prices seem to go together. High demand from a growing economy tends to hold prices up.

The label “China” refers to the rapid growth that took place in the decade after China joined the World Trade Organization in 2001. This was mostly powered by China’s huge growth in coal supply between 2002 and 2011 (Figure 6).

Figure 6. Production of coal for the World and for China based on data of the 2025 Statistical Review of World Energy, published by the Energy Institute.

China and the world experienced another spurt of increased coal production starting in 2022, when coal prices temporarily spiked to a high level, perhaps indirectly related to the conflict in Ukraine. But coal prices have gradually come back down, resulting in flat world growth in coal production since 2023, and a plateau in China’s coal production growth.

(c) Troubled Periods took place when the growth in “Living Standards” was low or negative

Figure 7 labels three periods with very severe dips in “Living Standards.”

Figure 7. This figure is similar to Figure 5, with three “Troubled Periods” labeled. There is also a small section added, extending the analysis to cover the period to 2025.

The First Troubled Period started with the Panic of 1857, which some consider to be a cause of the US Civil War. According to this view, the collapse was related to an over-expansion of the US economy, followed by the collapse of the debt bubble that had allowed this expansion to occur. Financial problems affected both the North and the South.

As I see the situation, one part of this financial problem was the declining profitability of slave labor. In the US South, the labor of slaves was the main source of energy used to operate plantations. An underlying issue was that the soil had gradually become depleted because of many years of growing of cotton and tobacco. These slaves had been purchased with debt; this debt could not be repaid with interest unless the income of the plantations was sufficiently high. However, poor harvests were not offset by sufficiently higher prices, which led to financial problems for plantation owners.

There may also have been an issue that the population, in general, was becoming poorer, essentially because of overpopulation. I say this because studies show that the height of army recruits had fallen, suggesting poorer nutrition. Sanitation had recently been improved, allowing a larger share of babies to survive to maturity. At the same time, immigration into the US continued. With overpopulation, it was difficult to keep incomes up. If farms were divided among many sons, farm sizes would tend to become smaller, leading to lower farm incomes. There would also be greater competition for factory jobs, tending to hold wages down.

Of course, when the Confederacy lost the war, the Confederate Dollar became worthless. For some, this added another financial crisis.

The Second Troubled Period was 1920 to 1940. This is a notoriously bad period, with the Great Depression and World War II included. Arguably, World War I should also be included. Commodity prices of all kinds fell very low. Tariffs were added in the 1920s. The problems seem to have arisen at the time Peak Coal hit–prices could not rise high enough to cover the cost of extracting coal from narrower and deeper seams. In my view, World War I began at the time of Peak Coal in the UK, and World War II took place at the time of Peak Hard Coal in Germany.

Figure 8. Chart showing coal production from my 2018 presentation.

With depletion, the cost of extracting coal kept rising, but the sales price of coal would not rise to compensate for the higher extraction costs. Instead, wages of miners were increasingly squeezed. Strikes and lockouts became common. Taking a job as a soldier seemed like a reasonable alternative.

There were many events from this period that most people would like to forget, including the currency hyperinflation of the Weimar Republic between 1921 and 1923 and the Holocaust from 1933 and 1945. Country lines were redrawn. Some countries disappeared, and new ones were added. Those holding currencies of countries that disappeared were likely left without funds.

The Third Troubled Period was 1990 to 2000.

A major event of the Third Troubled Period was the collapse of the central government of the Soviet Union, leaving the 15 republics as independent states. The collapse also indirectly affected Cuba, North Korea, and some countries in Eastern Europe that were not part of the 15 independent states. With this change, the demand for fuel of all kinds fell in the countries affected. Factories were closed in many areas, including Ukraine, which was part of the Soviet Union.

Figure 9. Former Soviet Union energy consumption by fuel, based on data of BP’s Statistical Review of World Energy 2018.

The pullback in demand from the collapse of the Soviet Union helped hold oil prices down in the 1991 to 2001 period. Oil prices had previously been brought down by the spike in interest rates in the 1980-1981 period. In my opinion, these low oil prices played a major part in the collapse of the Soviet Union. The Soviet Union, as an oil exporter, needed higher oil prices to invest in developing new fields. In my opinion, the impact of the collapse of the government of the Soviet Union kept world demand (and oil prices) low during the 1991 to 2000 period.

The collapse of the Japanese real estate bubble also took place in this period, as did the 1997 Asian Financial Crisis. Low growth in the world economy, indirectly related to the collapse of the Soviet Union, may have played a role in these financial events.

Figure 10. Slide from my 2018 presentation.

[3] The world’s self-organizing and self-healing economy

From a physics perspective, all economies are dissipative structures. Other examples of dissipative structures include ecosystems in general, all plants and animals, including humans, and hurricanes. One characteristic of dissipative structures is that, at some point in their lives, they tend to grow. Another is that if there is an injury, within a range, the systems tend to be self-healing. For example, a cut on a person’s arm will tend to heal; a hurricane going over land will temporarily lose much of its force, but it may increase in force again if it returns over warm water.

Another characteristic of dissipative structures is that they are dependent on having a sufficient energy supply of the right kinds to continue their existence. For humans, the energy supply is food; for an economy, it is a combination of many kinds of energy needed to match the built infrastructure of the economy.

All dissipative structures have finite lifetimes. Ecosystems often come to an end through fires. Humans generally do not live more than 80 or 100 years. Economies also tend to come to an end, either by losing a war or by the collapse of a central government, related to debt problems. The collapse of the Soviet Union involved a debt problem, among other issues. Figure 9 shows the huge drop in demand for energy of all types as its central government collapsed.

There is more stability of dissipative structures than a person might expect. Economists talk about an Invisible Hand being involved. Researchers examining dissipative structures talk about them being “self-organizing.” For example, if a fire or a change in climate causes a forest to collapse, it does not take many years for the forest to refill with suitable plants and animals for the somewhat changed situation. If a business or government fails, new, somewhat different businesses or governments are likely to take their place.

I would argue that if the Universe is constantly expanding (so it is an “open system,” rather than a “closed system”), what appear to be self-organizing systems may, in fact, be God-organized systems. In other words, instead of creation being a one-time event in the distant past, some type of literal higher power may be involved in a way that makes creation more or less an ongoing event. A person might wonder with the strange confluence of recent events, including the strange weather patterns associated with El Nino, whether today’s humans are being warned that a major change in economies will take place soon.

[4] What kinds of things may happen in the near future?

(a) Current disturbances in the Middle East and elsewhere are raising long-distance shipping costs for both food and oil. (See this video.) Normally, the price of food and oil must be high enough to satisfy producers and at the same time be low enough to satisfy customers. But now a new layer of costs has been added: the cost of shipping longer routes.

I would argue that because of the problem with low demand (affordability) by consumers, shipping costs must be paid almost entirely through a reduced net oil price available to oil producers and reduced net food prices available to farmers. The amount that consumers can afford doesn’t increase because of higher transportation costs.

(b) Furthermore, the use of extra oil for transportation of oil and food will tend to push the overall economy toward contraction because there will be less oil available for other uses, such as to power agricultural machinery and jet airplanes. If the overall economy begins to contract, we can expect dips in oil prices similar to those in 2008 and 2020 (Figure 1). But if recession persists, low oil prices will not reverse themselves as quickly as they did earlier.

(c) I expect home and farm prices will tend to fall around the world. This is related to the low level of demand (affordability problem) in the US and elsewhere. Figure 11, showing median US asking prices for homes, suggests that home prices have been barely holding their own for quite a while. A decrease would not be surprising with all the pressure the economy is now encountering.

Figure 11. Comparison of US median asking prices for homes from Realtor.com through June 2026.

Farm prices are likely to be under pressure as well, because of the difficulty farmers are having obtaining adequate income from their farms. If farm and home prices fall, there is a substantial chance that the debt bubble holding up these prices will collapse.

(d) There are many other debt bubbles that seem to be waiting to collapse. Some of the debt relating to AI seems to be in a bubble. There is considerable commercial real estate whose value seems to be being held up by “extend and pretend” loans. Collapsing debt bubbles tend to lead to collapsing banks. They also tend to lead to banks less willing to make new loans. Layoffs seem likely. All these things point to a major recession ahead, with less buying power for the population.

(f) Collapses of some top levels of government, similar to the collapse of the central government of the Soviet Union, may be ahead. Such collapses can greatly reduce world energy consumption, including oil, with relatively little violence.

[5] How the nature of the economy may help over the long term

As noted previously, economies seem to have self-healing properties. Troubled periods can last for many years, but there seems to be a substantial chance that a way out will eventually be found.

If a government fails because of excessive debt, a new government (or governments) is likely to take its place. The new government will likely have fewer employees and offer fewer services to citizens. Pensions will likely need to be reduced or eliminated completely.

Even if governments fail, or national boundaries are redrawn, I expect that some businesses will continue operations. Such a situation will take place even if a new currency needs to be created to make this happen. Even in a troubled period, new businesses will start operations. Some of these businesses will make use of recycled materials available from failing businesses.

According to the Maximum Power Principle, if there are resources available that can easily be used, somehow, some organization will develop a way to use them. Over the long term, the economy will likely re-organize itself in a way that is more complex and more sparing in energy use. If energy use is efficient enough, it seems likely that a higher price for that energy supply could be made affordable to consumers. But, such a transition may take many years, if it is possible at all.

Posted in Financial Implications, News Related Post | Tagged , , , | 3,966 Comments

Why Oil Shortages May Bring Lower Prices–and Recession

There have recently been many warnings about near-term oil shortages stemming from the conflict in Iran. Most analysts assume that shortages mean higher prices. As I will explain, the dynamics of a self-organizing economy suggest the opposite outcome — lower prices, deepening recession, and shortages of goods and services that have little to do with price.

A cartoon scene featuring a bluebird on a cliff, looking confidently at a surprised coyote who is about to fall off the edge, with a yellow sky in the background.
Figure 1. Wile E. Coyote and Road Runner cartoon showing Wile very surprised after he runs past the edge of the cliff. Source.

Rather than high prices, my major concerns are recession and the disappearing availability of goods and services that we rely on. This might be similar to the empty shelves that many stores experienced in 2020 and 2021. There may also be new government restrictions, intended to work around the reduced oil supply in a way that will allow essential services to continue to operate normally. Oil prices are likely to fall below $40 per barrel, as they did in 2020 with Covid restrictions.

In this post, I will try to explain why this counterintuitive outcome — shortages leading to lower prices rather than higher — is what the self-organizing economy tends to produce. Along the way, I will look at the current state of oil reserves, why the conflict with Iran is unlikely to be quickly resolved, and what the price behavior of oil since February 28 tells us. I will also step back to consider the broader picture: why war can seem like a solution to struggling economies, and what the 2020 Covid experience might teach us about what lies ahead.

[1] Reserves of already-pumped US oil have dropped to concerningly low levels.

On June 17, President Trump said, “We will run out of reserves in about four weeks without a deal.” According to the article, we are not certain whether Trump intended to apply this statement to US or world emergency reserves.

Also, according to this recent video, the US’s largest tank farm seems to be very close to the minimum level at which crude oil can be withdrawn from its tanks. And, on June 23, MSN said, “America may see actual gasoline shortages by July 4.”

The already-pumped oil in storage is intended to be used as a buffer if there are variations in supply or demand. The reason that these buffers are falling low is because considerable oil from them has already been used to mitigate the shortfall in crude oil supply to date.

The shortfall in the supply of crude oil supply cannot be expected to disappear quickly. There has been considerable damage to infrastructure in Iran and elsewhere. It will take years rather than months for this to be repaired. In countries where oil production has been shut in, some wells are likely to produce less after being reopened following many months of closure. Furthermore, Iran has no incentive to completely reopen the shipping lanes, since keeping them potentially closed has the potential to raise oil prices per barrel. Higher oil prices would help the finances of Iran.

[2] Perhaps because of concern about low buffer supplies, the US has negotiated a deal with Iran that seems unfavorable to the US.

Information keeps coming out that indicates that Trump’s current Memorandum of Understanding (MOU) is very favorable to Iran. It looks as if the MOU has been written as if Iran won the war. We are also seeing that other countries have begun acting as if Iran has indeed won the war. For example, on June 23, a joint statement was issued by Iran and Oman. The two countries seem to be co-operating in setting up the collection of funds from ships passing through the strait to cover insurance and other costs.

If we are dealing with a “done-deal,” and the US is coming out poorly, the level of conflict within the US is likely to rise. Many people will be angry with Trump for getting the US into the war to begin with. Unfortunately, there is likely close to nothing we can do about this situation.

[3] Trump or another leader cannot restart the war against Iran and expect to do any better.

A major problem is that the US has substantially depleted its ammunition supplies, and it will take years to replenish them. While the US could perhaps launch a short attack, it would not be able to carry out a sustained campaign for very long.

Another issue is that the armaments that the US has stocked to date are designed to be used in a different type of war than the one that is being fought today. The US needs drones and close-by locations from which to launch them. Iran damaged most of the US’s bases that are close to Iran in the conflict that began on February 28. Without substantial rebuilding, the US has no functioning bases close to Iran from which to launch such drones.

Restocking armaments will likely take several years, especially if new types are needed. Adding to the difficulties of the US is the fact that China has been the primary source of many critical minerals used in the production of high-tech goods and ammunition. In recent years, China has restricted access to these critical elements. The US is now developing mines for some of these minerals, but setting up entire supply chains will take years.

[4] One motivation for attacking Iran might have been to raise oil prices to a higher level.

Based on their models, economists typically reach the conclusion that inadequate oil supplies will lead to high oil prices. It is likely that President Trump and his advisors believed that inadequate oil supply would lead to high oil prices.

Some analysts, including me, would argue that the models of economists are very inadequate; they give misleading indications by leaving out the complex self-organizing nature of the economy.

Higher oil prices are sometimes desirable because they encourage more oil extraction. For example, higher prices allow marginal wells to continue to be profitable longer. They can also make a new, higher-cost source, such as tight oil from shale, attractive for drilling. Looking ahead, higher oil prices would make it easier to get oil company support for ramping up oil production in Venezuela.

Figures 2 and 3 show the connection that higher oil prices seem to have had in encouraging tight oil extraction from shale. Figure 2 shows historical oil prices, adjusted for inflation. Noted on this figure is my view of whether prices were high enough to encourage extraction from more difficult locations.

Line graph showing the trend of Brent equivalent oil prices from 1925 to 2025, with annotations highlighting periods of low prices affecting extraction costs. Key points include 'Low cost of extraction; Low sales price - All happy' and 'Prices again too low'.
Figure 2. Figure showing historical average annual inflation-adjusted oil prices, based on data of the 2025 Statistical Review of World Energy, published by the Energy Institute. The 2025 average oil price is estimated based on EIA data. Comments on price levels have been added, as well. An underlying issue is that the price of oil extraction has tended to rise faster than inflation.

Figure 2 indicates that prices started to run up in the 2003 to 2008 era, when China started ramping up its manufacturing, and thus its demand for oil. In this same timeframe, there was also a growing demand for housing in the US, thanks to very liberal underwriting standards for home mortgage loans. Thus, the total demand growth for oil was very high.

Figure 3 shows that production of tight oil started ramping up in 2009, after oil prices had been rising for several years.

Graph depicting monthly U.S. tight oil production by formation, measured in million barrels per day from 2009 to 2025. Notable formations include Permian, Bakken, and Eagle Ford, with a significant rise in production levels over time.
Figure 3. Monthly tight oil production in figure produced by the EIA

Another factor in the growth of tight oil production was the availability of cheap credit after 2008, but this has tended to disappear since 2021. Now, tight oil production seems to be leveling out, leading to rising concerns that tight oil production may soon decline, especially if credit is no longer cheap. Having higher oil prices might help postpone the decline of tight oil.

[5] Oil prices since the war started on February 28 have not bounced very high. Recently, they have tended to fall back, close to their pre-war level.

A line graph showing the WTI oil price trend from February to June, indicating fluctuations around $60 to $140, with a notable increase following the marked date 'Iran Conflict Began' on February 23.
Figure 4. West Texas Intermediate benchmark oil prices, mostly based on EIA data. Most recent points based on Wall Street Journal charts. Amounts through June 26, 2026.

The first thing to note is the fact that the prices on Figure 4 do not reflect the actual prices to the consumer, which have often been greater. The cost of transporting oil has jumped in many markets, but this higher transport cost is not reflected in the “West Texas Intermediate” price of oil, displayed in this chart. These higher prices at the pump have led some of the more price-sensitive buyers of oil products to cut back on their purchases.

Second, there is a lag issue regarding how soon the impact of missing supply actually hits the market. The slow transit time of oil from the Middle East to markets means that the actual disruption of supplies did not hit until at least 50 days later. If crude oil first needs to be processed by local refineries and then the oil products shipped to customers, the lag would be even greater–perhaps 75 or 100 days in total. Thus, much of the price increase to date may be based on a fear of shortages, rather than on an actual shortage issue.

Third, there have been some changes that impact oil “demand.” Some consumers have been told by their governments to work from home or otherwise restrict their driving to save on oil consumption. Also, some flight schedules have been cut back. Recently, Ukraine has been targeting some of the oil infrastructure of Russia, leading to reduced gasoline and diesel availability within that country. All these issues have tended to reduce the demand for oil. The lower demand acts to hold down oil prices.

A fourth issue has to do with worldwide economic conditions before February 28. Even before the war, much of the world was in close to a recessionary situation. There were very many low wage earners who could not afford much beyond the basic necessities of life. Even a small run-up in oil prices tends to affect food prices because oil is often used in farming operations and food is usually transported to market using oil. With higher food prices, poor consumers were forced to cut back on other purchases. This recessionary dynamic can be expected to get worse if oil prices inch up even a bit.

[6] I expect that oil prices will continue to remain relatively low, or they will only briefly rise to high ($150+) levels, even if there are actual oil supply disruptions.

I expect that the dynamics we have been seeing since February 28 will continue, and may intensify. Governments will add new restrictions that will reduce oil use. Airlines will go bankrupt, or they will reduce flight schedules. Recession will become even more of a problem. These issues will tend to reduce usage without raising prices.

[7] What we may see more of is broken supply chains.

There will be more signs in grocery stores and in home product stores saying, “This product is temporarily unavailable.” Car repair shops may tell us that a required replacement part will not be available for several months. Physicians may tell us that a medicine or chemotherapy drug that they normally use is, at this time, unavailable.

[8] The operation of the economy depends on an adequate supply of many kinds of energy. If oil supply is reduced, an economy needs to shrink to a smaller size to match. This is what leads to recession.

One reason for the above observation is that we know that our own vehicles will not operate without whatever fuel they are designed for. This is clearly also true for all the delivery trucks in the world, and for farm machinery and for ships that transport goods across the ocean. With less fuel, fewer trips of many kinds will be made. Workers will be laid off. This dynamic sounds a lot like recession.

The expected lower world oil supply in the near future is not an issue that can easily be resolved. We are already seeing that even with a supposed settlement, disruption in oil supplies seems likely to continue and even to worsen, as the various limits on buffer supplies are reached. Unfortunately, we cannot expect the situation to be completely fixed for several years.

Furthermore, the economy is facing even more disruptions than I have outlined above. For instance, Ukraine has been disrupting Russia’s oil infrastructure with drone attacks. There have also been disruptions to sulfur exports from the Middle East. Sulfur is used in many ways, including as a fertilizer and in the production of sulfuric acid, which is used in the mining of uranium, among other things. In addition, there have been disruptions to liquefied natural gas (LNG) exports from Qatar. The lack of these important products will tend to further damage supply chains and lead the economy deeper into recession.

[9] We are ultimately dealing with multiple not-enough-to-go-around scenarios. This situation will tend to increase conflict in the world.

The dynamic we are dealing with is similar to that in the game of Musical Chairs.

Seven red chairs arranged in a circular formation, casting shadows on a white background.
Figure 5. Chairs arranged for Musical Chairs Source: Fund Raising Auctioneer

The game of musical chairs is played in rounds. Players walk around the edge of a circle of chairs while music is played. When the music starts, the number of players is equal to the number of chairs. In each round, one chair is removed. The music plays and then suddenly stops. The players must then scramble to grab a chair. Since the number of chairs is now one fewer than the number of players, small fights can ensue.

The problem is basically, “Not enough to go around.” War often sounds like a reasonable solution to leaders.

[10] War can seem like a solution.

Strangely enough, war has multiple advantages to economies that are suffering from difficulties related to low commodity prices and, indirectly, low wages in related industries. One commodity is food. If food prices are too low, farmers will be unhappy that their earnings are low. They may stop farming and try to make a living from putting their land into a land bank and working elsewhere.

If oil prices are low, the oil industry can experience pockets of low wages. There have recently been reports of lockouts and strikes in the oil industry. I would expect these labor actions to be most prevalent where oil fields are depleted.

If a government announces a war, it looks like the government is “doing something” about the country’s problems. There is suddenly employment, either as a soldier, or in building armaments. GDP tends to rise because the war leads to a larger share of the population working. The war can be used to justify the additional government debt needed to hire the additional workers. What convinced me of this relationship was this chart, showing a huge increase in US GDP during World War II:

Line graph showing the US 3-year average percentage change in real GDP from 1932 to 2024, with fluctuations highlighted during the 1940s and gradual stabilization in later years.
Figure 6. Three-year average increases in US inflation-adjusted GDP, based on data from the US Bureau of Economic Analysis. The last point is 2025.

Looking closely at the chart, it is also possible to see GDP increases during the Korean War (1950-1953) and between the time the US entered the Vietnam War, deploying up to 549,000 soldiers, and the time the US greatly reduced its forces there (1964-1969).

I think much of Europe is now in a situation in which war looks like a solution. Russia may also be in such a situation. Ukraine, with its problems, is also in such a situation.

[11] There may be lessons to be learned from the 2020 Covid restrictions and the ultra-low oil prices that resulted then.

Back in 2019, many people in the financial world were concerned about the economy. In 2019, the US faced significant financial issues, including a budget deficit that increased by $205.4 billion to $984.4 billion. In addition, in September 2019, there was a spike in the interest rates financial institutions charge each other (repo rates) that concerned those who followed financial markets closely.

What took place in 2020 seemed to some of us to be close to miraculous. The strange actions related to Covid greatly brought down the price of oil. Covid also provided an excuse to give money to households. US government debt was able to increase greatly, and, somehow, the world economic system has held together until now. Financial problems were “kicked down the road” a while longer. Without the pressure of financial problems, the economy could work on ways to mitigate the energy problem a while longer.

Economies are self-organizing systems, just as the human body is a self-organizing system. Both are powered by “energy dissipation.” Human bodies tend to heal wounds, like magic. Economists talk about an “invisible hand” being helpful to economies. In situations where the healing of economies does occur, low oil prices can be part of the magic.

[12] What might be ahead?

We are again in a period when the US and world economies are on shaky ground. Debt levels are high, and conflict levels are high.

As I have discussed in this post, I expect the general trend in oil prices will be down, rather than up. The major reason why oil prices are likely to be low is because, with the damage done in the Middle East, the quantity of oil supply available to the world is starting to shrink. As a result of the low oil quantity, the world will produce fewer goods and services. This is close to the definition of recession! (Also, on Figure 1, this is why we expect Wile E. Coyote to fall down, rather than to float up, when his support disappears.)

I expect as oil product shortages hit, local leaders will figure out ways to mitigate the oil bottleneck that the world now seems to be facing. Local leaders will enact rules that make certain that whatever oil is available is used to maintain essential services. It will not be surprising if local leaders keep people at home, using one excuse or another, to keep oil demand in line with the quantity of oil that is available. This is a big part of why oil prices will tend to be low, in a manner similar to 2020.

With low oil prices, I expect that inflation will be low. Pressure to keep raising interest rates will disappear. The economy will not be doing well, but the issue will not be high interest rates preventing new investment.

In my opinion, the world economy needs to reorganize with shorter supply lines to get through the oil “tight spot” that the economy is in. If supply lines could mostly be kept within the areas marked on Figure 7, it seems like a significant amount of transport fuel could be saved.

A world map with highlighted areas in yellow representing parts of North America and East Asia, surrounded by a black outline.
Figure 7. Map showing world divided into two areas of influence. In my opinion, supply lines need to increasingly come from within the same hemisphere. Areas marked in yellow represent my idea of future centers of trade.

The conflict with Iran doesn’t seem to be ending well for the US, but there might be a silver lining. The pain the US is experiencing in Iran will hopefully teach the US to stay out of issues in the Eastern Hemisphere. If a conflict with Iran is to ramp up again in the near future, I expect that it will be a European group that will be getting involved, not the US.

We don’t know quite what is ahead, but the experience in 2020 shows that a strange confluence of events leading to low oil prices can actually be helpful. Let us hope that a similar result will be possible this time.

Posted in Financial Implications, News Related Post, oil shortages | Tagged , | 3,026 Comments

China and US Trade Talks: A Solution for Oil Shortages?

The war with Iran is not going well. It is difficult to supply US troops with adequate food and other necessities. With summer arriving soon, the region will soon be an even more inhospitable place for ground troops to fight. An underlying problem is that the world economy was reaching resource limits even before the Iran War began, adding to the difficulties.

The most pressing resource limit is distillate fuel oil–an industry term for what we think of as diesel and jet fuel. This fuel is heavily used in transportation. It is also used extensively in agriculture and industry. Somehow, the system needs to cut back on these fuels for international trade so that more fuel is available for agriculture and industry.

President Trump of the US and President Xi of China will be meeting in Beijing on May 14-15. This meeting would seem to be the perfect time to start reorganizing the world with shorter trade routes, so that the world economy uses less fuel for transportation. China and the US are the two great powers in the world. Keeping trade mostly within the two areas shown in Figure 1 would be a way of using fuel oil more sparingly.

A simplified world map highlighting two regions in yellow: one in North America and one in East Asia.
Figure 1. Map of the world showing how Gail Tverberg expects Presidents Xi and Trump might split most world trade. The vast majority of trade would take place within the two areas shown. Within these groupings, the centers of trade might be the yellow areas shown.

An advantage of such a plan, besides saving on fuel, is that it could stop the Iran War without clearly declaring one side the winner or loser. In this post, I will attempt to explain the situation further.

[1] Based on the ideas of Dr. Mohammed Marandi, I believe that China might be able to mediate a settlement between the US and Iran.

Dr. Marandi was born in the United States of Iranian parents. He currently lives in Iran, where he is a professor at the University of Tehran. In the video, One Country Quietly Won this War, he points out that, often, when two countries battle each other, neither one emerges as the clear winner. Both of them are damaged by the war. The actual winner may be a country that does not seem to be directly involved in the war.

In the video referenced above, Dr. Marandi discusses three historical situations in which a nation not directly involved in a conflict gained stature by being the “adult in the room,” when two other nations battled each other. In this case, Dr. Marandi believes that China could very well be the country that can exert enough pressure on both sides to get them to accept a proposed solution. He says that China has acted behind the scenes to bring about the ceasefire, and that Trump has acknowledged China’s role.

Dr. Marandi suggests the idea that the upcoming meeting of the two presidents might be an opportune moment to make major steps toward a mutually agreed settlement. I believe that the underlying problem is that there isn’t enough energy (particularly oil) to support a world population of over eight billion. Dividing up markets in the way I have suggested would at least somewhat alleviate the shortage. Of course, there may be other terms of a settlement, as well. In addition, not all the terms may be determined precisely at this time.

[2] The world doesn’t have enough diesel and jet fuel to maintain the current level of trade across the Atlantic and Pacific Oceans.

Line graph showing world per capita diesel and jet fuel consumption from 1980 to 2024, indicating a small peak in 2007 and a major drop in 2020 with only partial recovery afterward.
Figure 2. Combined diesel and jet fuel supply, divided by world population, based on data of the 2025 Statistical Review of World Energy, published by the Energy Institute.

Figure 2 shows that per capita diesel and jet fuel started to drop at the time of the Great Financial Crisis in 2007-2009. Their supply took a larger step down in 2020, and it hasn’t completely recovered. In 2026, the Iran War has taken out more crude oil supply, for an unknown period of time.

Diesel and jet fuel are both very important as transportation fuels. Diesel is also important in agriculture because it provides the power needed for heavy machinery to till fields, even under the most adverse conditions. Diesel provides the power needed for large commercial trucks, many trains, and ships. Earth moving equipment is also typically operated by diesel fuel.

If the amount of trade across the Atlantic and Pacific could be greatly reduced, it would help alleviate the shortage of distillates. Of course, the tourist trade would also need to be greatly reduced. With recent spikes in aviation fuel prices, many flights are being cut. Some airlines, including Spirit Airlines in the US, are going bankrupt. The problem is starting to solve itself, but more changes will be needed.

[3] Looking at population and oil supplies, the Americas seems likely to come out somewhat ahead.

[3a] Comparing the populations of the two areas, the World ex Americas is much larger, and its population is growing faster.

Line graph depicting global population growth from 1980 to 2024, comparing populations in the Americas (blue line) and the world excluding the Americas (orange line).
Figure 3. World population between the Americas and the world excluding the Americas, based on data of the 2025 Statistical Review of World Energy, published by the Energy Institute.

President Xi (leading one hemisphere) would get the very large and still rapidly growing part of the world population. President Trump would get a smaller and less rapidly growing share of the world population. Between 2021 and 2024, world population grew an average of 0.6% per year in the Americas, and an average of 0.9% per year in the World ex Americas.

[3b] The Americas seem to have an advantage with respect to crude oil production.

Line graph depicting crude oil production per capita from 1980 to projected 2025, showing two lines: one for the Americas (blue) and another for the world excluding the Americas (orange).
Figure 4. Crude oil production per capita, based on data of the US Energy Information Administration.

It makes sense to look at energy amounts on a per-capita basis because the quantity needed depends on the number of people requiring the benefits of transportation, agriculture, and industry. On this basis, crude oil production of the Americas has clearly been outshining that of the World ex Americas. It is higher on a per-capita basis. In addition, the amount available has been increasing in recent years.

Figure 5, below, shows total crude oil production (not per capita).

Line graph showing crude oil production from 1980 to 2025, with two lines: one representing 'Americas' in blue, and another representing 'World ex Americas' in orange. The y-axis measures production in million barrels per day.
Figure 5. Crude oil production of the Americas compared to that of the World ex Americas, based on data of the US Energy Information Administration.

Figure 5 suggests that since 2005, crude oil production for the World ex Americas has hardly increased. In fact, total extraction has decreased since 2019. A person viewing this data might conclude that crude oil production in this area may already be past its peak.

On the other hand, Figure 5 shows that oil production of the Americas has increased by about 65% since 2005. Many people believe that US shale production will soon decline. At the same time, however, increases seem likely in several other countries in the Americas, including Canada, Brazil, Argentina, and Guyana. Thus, while crude oil production for the Americas may decline in the near future, its decline is likely to be gradual.

[3c] Crude oil production by geographical area outside of the Americas shows declining production in all areas.

Line graph showing crude oil production by area, excluding the Americas, from 1980 to 2025. The graph features multiple colored lines representing Europe, Asia Pacific, Africa, Russia+, and the Middle East, with production in million barrels per day.
Figure 6. Crude oil production by geographical area for the World ex Americas, based on data from the US Energy Information Administration. Russia+ refers to Russia plus nearby countries that used to be part of the Soviet Union.

Figure 6 shows that Europe’s crude oil production started its permanent decline in 2001. Asia-Pacific’s production hit a maximum in 2010, and it has been declining since. Africa’s peak oil production took place in 2008, and it has been mostly declining since.

Russia+, which I use to refer to Russia plus nearby countries that used to be part of the Soviet Union, has an unusual production pattern. Its crude oil production started to decline in 1989, two years before the collapse of the Soviet Union in 1991. (This collapse in crude oil production likely contributed to the collapse of the Soviet Union.) Crude oil production for Russia+ rose from 1998 to 2019.

Russia+’s production took a big step down in 2020, and it has not been able to recover since. A person might think that Russia+’s oil production was post peak, even before the 2022 conflict with Ukraine broke out. If an oil exporter doesn’t have enough oil to export, it tends to create financial problems within an economy. Participating in a war can appear to mitigate the country’s problems.

Many people assume that the Middle East has endless inexpensive-to-produce crude oil. I don’t think that this is the case. Crude oil production of the Middle East (Figure 6 above) hit two similar peaks in 2016 and 2018, and it has been lower in years since then. I think that Middle Eastern oil production is likely past peak partly because of depletion issues and partly because most countries in the area require high taxes on oil exports to provide subsidies for their ever-growing populations. This leads OPEC to try to maintain high prices. Lower crude oil production since 2018 is consistent with the hypothesis that oil production for the Middle East is mostly post-peak.

One additional difficulty of the World ex Americas is that it is so heavily populated that it cannot access tight oil that might be available without displacing a large number of residents. Another difficulty is that very old wells, such as those in Saudi Arabia and Iran, are ones that it might not be possible to restart if they are shut in for an extended time.

[4] In terms of mining and manufacturing, the Americas seems to come out behind the World ex Americas.

The World ex Americas has rapidly ramped up mining and manufacturing. Coal has been the preferred industrial fuel, with natural gas consumption also increasing.

Line graph depicting global energy consumption by type (Oil, Coal, Natural Gas, Fossil Fuel Extenders) from 1980 to 2022, measured in Exajoules.
Figure 7. Energy consumption by type for World ex Americas, based on data of the 2025 Statistical Review of World Energy, based on data of the Energy Institute. Fossil fuel extenders include hydroelectric power, nuclear power, wind power, solar power, biofuels including ethanol, and any other types of add-ons to fossil fuels.

Figure 7 shows that the energy consumption of the World ex Americas started increasing more rapidly after China joined the World Trade Organization in 2001. The consumption of coal and natural gas has especially increased.

Line graph displaying energy consumption by type in the Americas from 1980 to 2022, showing oil, coal, natural gas, and fossil fuel extenders in exajoules.
Figure 8. Energy consumption by type for the Americas, based on data of the 2025 Statistical Review of World Energy, based on data of the Energy Institute.

The economies of the Americas have tended to shift towards service economies. Emphasis has been placed on fuel efficiency. Homes are now better insulated, light bulbs are more efficient, and engines of vehicles are more efficient. As a result, energy consumption within the Americas has tended to stay flat (Figure 8).

I have used the same scale on Figure 8 as on Figure 7 to emphasize how low energy consumption for the Americas is now, relative to the rest of the world. After US oil prices first rose to a high level in 1973, the US started transferring manufacturing to lower-wage countries. Southeast Asian countries began to be favored after 2001. Moving manufacturing abroad helped hold down US energy consumption and helped make the cost of goods to the consumer cheaper.

The problem today is that moving so much manufacturing elsewhere has made it difficult for the Americas to go back to producing its own goods, including clothing, furniture, and transformers for electrical systems. Supply lines for a particular item, such as a refrigerator, often run through many countries around the world.

[5] The full transition to the configuration shown on Figure 1 could take well over 100 years.

Changes, such as new supply lines and the new placement of major population areas, cannot happen very quickly. But I expect that some of the same underlying principles that guided these decisions in the past will continue to guide them in the future.

For example, infrastructure (roads, bridges, pipelines, and (today) long distance electricity transmission lines) seems to be the most difficult part of an economy to maintain because of the huge amount of energy required. Before the days of fossil fuels, I understand that slave labor was often used to build and maintain infrastructure. Similarly, slave labor was sometimes used to staff the mines needed to support the building of such infrastructure. As we lose fossil fuels, we will need to think about reducing our reliance on infrastructure.

One low-infrastructure approach used in the past was to build cities near bodies of water, so that fewer roads would be needed. Boats could be used to transport goods without building roads or bridges. If fish were available, they could be caught and used for food. In Figure 1, I am imagining that we will head back in this direction, with cities especially along navigable bodies of water and the ocean.

Unless we discover ways to replace fossil fuel energy, I would expect that the system will tend to go down in the reverse order of when it was put up. In general, electricity was last to be added, after coal, oil, and gas from coal. Electrification was first built in cities; then electricity transmission lines were added to provide electricity to rural areas. Above-ground lines tend to be damaged in storms, leading to a need for frequent repairs. Because of this issue, I would expect rural electricity to disappear quite quickly, unless it is generated at the location where it is used.

Natural gas shipped as Liquefied Natural Gas (LNG) was added very late. Its cost tends to be much higher than that of pipeline gas. I expect it to disappear quite quickly.

A full transition to the two trading zones shown on Figure 1 would require a huge number of changes in supply lines. A 2025 chart by Visual Capitalist shows how much control China has over critical minerals. It states, “China controls key materials such as graphite, rare earths, and gallium–essential for green technologies and defense industries.” While the US has started working on its own production of minerals, it will also need to develop the processing capability for these minerals. Putting all of this in place will likely take many decades. This is a significant factor in the 100-year estimate.

[6] If energy supplies are limited, I would expect population centers closest to fuel sources to be especially favored.

Writers today talk about possibly running short of diesel and jet fuel in a few weeks or months. Clearly, if a population center is at a location where there are both oil wells and refineries for the oil from those wells, the area has a better chance of having fuel than an island in the middle of the Pacific with nothing to sell other than tourism. Thus, Houston, Texas, will likely have fuel, even when models suggest there will be shortfalls in many places.

Often writers concerned about resource shortages talk about the core and the periphery. The core needs to be near whatever source of energy is available that can be used to help grow crops and transport goods. At this point, oil is the fuel that is closest to filling this need. Electricity is a nice-to-have, and it can provide services like refrigeration for food. But it is not good for paving roads or building bridges. So, it can only add to the mix, not substitute completely for oil. Slave labor is the closest substitute for oil that the world has discovered. We would rather not go back to using such an approach.

[7] I am concerned that a major downward economic step will be necessary in the upcoming months and years, but I am hopeful that the meeting between President Trump and President Xi on May 14-15 can help smooth the way.

We are at a point at which it is clear that the current organization of the global economy is not working. I hope that the meeting between Trump and Xi will help put an end to fighting in the Middle East. I also hope it will help pave the way for a new path forward.

I expect that the path ahead will be a difficult one, both for the people in the Americas and the people in the World ex Americas. While the US has considerable energy supplies, it lacks manufacturing capability for many everyday goods. The US is also lacking in many critical minerals, especially those used in making high-tech products. With its high wages, it will need extremely high prices, unless processes can be made very efficient.

The World ex Americas may have an even more difficult step down. Its oil supply was already more stretched before the Iran War. Its overpopulation problem seems to be worse than that of the Americas. The World ex Americas is more directly affected by the damage done in the Middle East and the resulting loss of oil supply. And there seem to be many groups looking for war, even if the US leaves.

Let’s all keep our fingers crossed that the upcoming meeting will have a beneficial effect, both in the short term and in working toward a longer-term solution.

Posted in Energy policy, News Related Post, Oil and Its Future, oil shortages | Tagged , , , | 3,235 Comments